How to Track Your Net Worth Monthly: A Simple Method That Actually Sticks
- Primary Signal: How to Track Your Net Worth Monthly: A Simple Method That Actually Sticks
- Overview: Net worth — everything you own minus everything you owe — is the clearest single measure of financial progress. This guide shows how to set up a simple monthly tracking spreadsheet...
- Verification: Analyzed and compiled by FreeRich AI Hub editorial monitoring desk.
A budget tells you where your money goes each month. Net worth tells you whether you are actually getting ahead. It is a single number, calculated by subtracting everything you owe from everything you own, and tracking it monthly turns vague financial anxiety into a clear trend line. The habit takes less than thirty minutes a month once it is set up, and it is one of the most honest measures of financial progress available.
Net worth is simply total assets minus total liabilities. Assets include cash in bank accounts, investment and retirement account balances, the current value of property you own, vehicles at a realistic resale value, and any other items you could realistically sell. Liabilities include mortgage balances, car loans, student loans, credit card balances, personal loans, and buy-now-pay-later balances still owed. The result can be positive, zero, or negative, and a negative number is not a crisis: it is common early in life, when student loans or a new mortgage outweigh accumulated assets. What matters is the direction of the number over time, not any single month's figure.
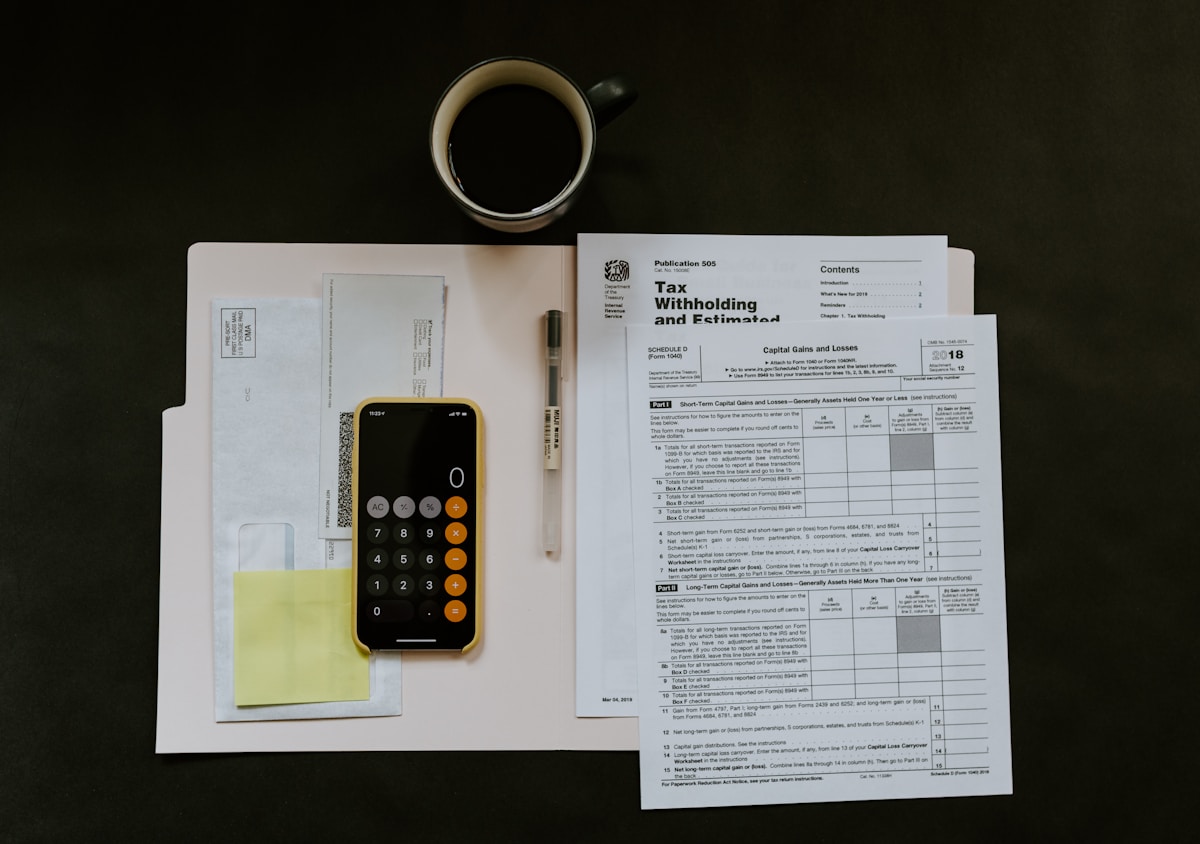
A basic spreadsheet is all you need, and it beats most apps for beginners because it is transparent and flexible. Create one row per account and one column per month. Label each row as an asset or a liability and group rows into categories such as cash, investments, retirement, property, and debt. At the bottom, add three rows: total assets, total liabilities, and net worth, calculated as assets minus liabilities, plus a change row showing this month's net worth minus last month's. Enter debts as positive numbers in the liability rows so the formulas stay easy to read. A line chart of the net worth row, added once a few months of data exist, makes the trend visible at a glance and is surprisingly motivating.
Pick one fixed day each month, such as the first weekend of the month, and spend about twenty minutes on the update. First, log into each bank, brokerage, and retirement account and record the current balances. Second, check each loan for its current payoff balance, not the monthly payment: a car loan with a monthly payment is still a liability equal to its full remaining balance. Third, check credit card statements for current balances, using the same balance type each month for consistency. Fourth, enter the numbers, let the formulas calculate the totals, and record the result. Fifth, compare this month's figure with last month's and note what drove the change: a debt payment, a market move, a large purchase, or an irregular expense. That short note is what turns raw numbers into understanding.
Consistency matters more than precision. For your home, use a conservative estimate and the same method each month, such as the purchase price plus a modest yearly adjustment or an online estimate minus selling costs. For vehicles, use a realistic private-party value from a pricing guide rather than the purchase price. For investments, use the balance on the same day each month. For debts, always use the payoff balance. Avoid the temptation to inflate asset values to make the number look better: the point of tracking is an honest picture, and a flattering but false number helps nobody. Some people exclude vehicles entirely because they depreciate, which is fine as long as the choice stays consistent month to month.
Monthly is the sweet spot for most people. Weekly updates mostly show market noise and can tempt you into reactive decisions, while yearly updates are too far apart to stay motivating or to catch problems early. A reasonable refinement is to update account balances monthly but refresh slow-moving valuations, such as property and vehicles, only once a year, which keeps the routine quick without losing accuracy. After a major life event, such as a job change, a move, or taking on a mortgage, do a full update across all accounts so the new baseline is accurate. The habit should feel light: if the routine takes more than thirty minutes, simplify the spreadsheet rather than abandoning the tracking.
Tracking only helps if it informs a decision. Each month, after recording the figure, pick one next action based on what you see: pay down the highest-interest debt, increase the savings transfer, start or top up an emergency fund, or review investment fees. Over time, the trend line shows whether those actions are working, which is far more useful than any single month's number. After twelve months of tracking, most people find they understand their finances better than any budgeting app could teach them, because the record shows exactly where money came from and where it went. Start today with a simple spreadsheet, four columns, and one honest snapshot; the trend you build over the coming year will be the clearest picture of your financial life you have ever had.
📖 Continue Reading the Full Story
Continue reading this article on FreeRich AI Hub.
⚡ Access Full Content NowMore from FreeRich AI Hub



 📦 Free2Rich Vault
The Pay Yourself First Budgeting Method: A Step-by-Step Guide for Beginners
The pay yourself first method flips the usual budgeting order: savings leave your account on payday, and you b...
 🎮 GameVault 668
How to Create a Favicon for Your Website Free: A Complete Guide
A favicon is your brand's smallest ambassador. This guide shows how to design one that reads at 16 pixels, gen...
 💎 LuxeLiving 768
How to Check DNS Records of a Domain: A Beginner's Guide
Checking a domain's DNS records takes under a minute once you know the tools. This guide covers online lookup ...
🐋 CryptoAce VIP
How Do Crypto Mining Pools Work and Are They Worth Joining in 2026?
A mining pool combines thousands of miners' hashpower and splits block rewards proportionally, turning solo mi...